
Is Kuda a Microfinance Bank or Digital-Only Platform
Is Kuda a Microfinance Bank or Digital-Only Platform? Discover the truth about Kuda’s services and find out how it can revolutionize your banking experience!
What Are the Types of Microfinance Institutions Worldwide
Unlock the secrets of microfinance! Discover the diverse types of microfinance institutions worldwide and learn how they empower communities. Start your journey today!
How Microfinance Help in Alleviating Poverty: Real Impact

Discover how microfinance truly helps alleviate poverty and transforms lives. Learn impactful strategies and real-world successes that inspire change today!
How to Start a Microfinance Institution: Planning & Launch

Launch your microfinance institution with confidence! Discover essential planning steps, strategies, and real-world insights to empower communities today.
What Is Joint Liability Group in Microfinance: How It Works
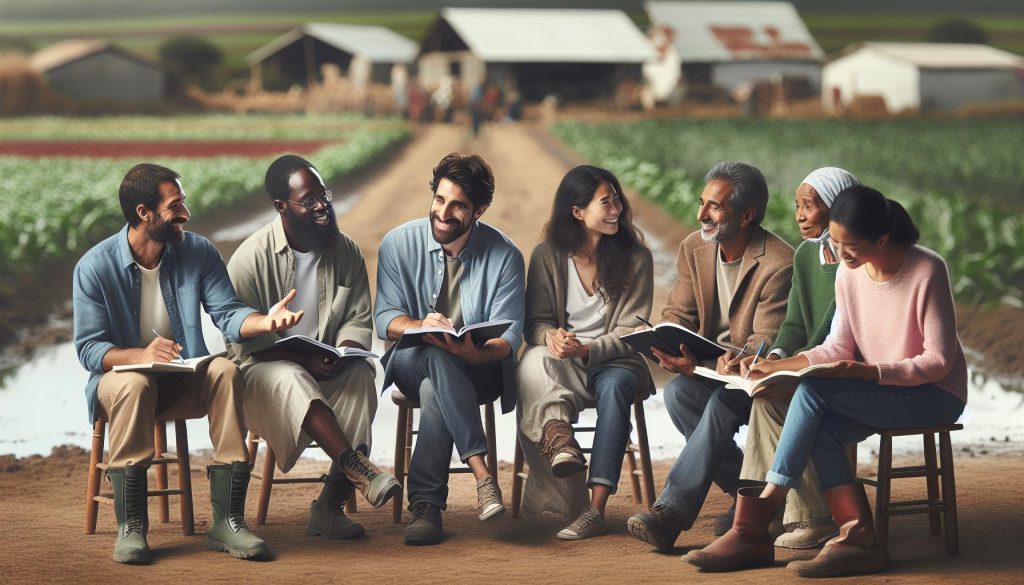
Discover how Joint Liability Groups in microfinance empower borrowers! Learn how they work and can transform your financial journey. Take control today!
Is Microfinance Good or Bad: Weighing Benefits vs Drawbacks
Is microfinance good or bad? Discover the hidden benefits and drawbacks that could impact your financial choices. Learn how it shapes lives today!
What Are Microfinance Institutions in India: Leading Players

Unlock financial empowerment! Discover how microfinance institutions in India are transforming lives. Learn about the leading players and their impact today!
Is Kuda Bank a Microfinance Bank: Regulatory Classification
Is Kuda Bank a microfinance bank? Discover its regulatory classification and what it means for your finances. Learn how this impacts your banking choices today!
What Are Microfinance: Definition & Types Explained Simply
Unlock the potential of microfinance! Discover its definition and types, and learn how it can empower you financially. Start your journey today!
How to Get Loan from Microfinance Bank: Approval Tips
Unlock quick funding with “How to Get Loan from Microfinance Bank: Approval Tips.” Discover essential strategies for swift approval and start your journey today!
Foundational Pillars (Start Here)
Is Kuda a Microfinance Bank or Digital-Only Platform
Empirical analysis evaluating operational frameworks, syndication mechanics, and grassroots capital access.
What Are the Types of Microfinance Institutions Worldwide
Empirical analysis evaluating operational frameworks, syndication mechanics, and grassroots capital access.
How Microfinance Help in Alleviating Poverty: Real Impact
Empirical analysis evaluating operational frameworks, syndication mechanics, and grassroots capital access.
The Grameen Revolution and Modern Financial Inclusion: From Microcredit to Digital FinTech
Pioneered by Nobel Peace Prize laureate Muhammad Yunus and the Grameen Bank in Bangladesh, microfinance shattered the banking myth that poor individuals are uncreditworthy. By replacing traditional physical collateral requirements with peer-based social collateral—most famously through Joint Liability Groups (JLGs) and group lending circles—microfinance institutions (MFIs) demonstrated historical loan recovery rates exceeding 95% while providing vital working capital to women entrepreneurs.
In the modern era, microfinance is undergoing a profound digital transformation. Mobile money architectures, biometric digital identity systems, and branchless agent networks (such as M-Pesa in East Africa and digital microfinance banks in West Africa and India) have drastically lowered transaction costs. By integrating algorithmic credit scoring and transparent repayment structures, modern MFIs empower smallholder farmers and community artisans to build resilient household balance sheets.
| Microfinance Mechanism | Collateral Archetype | Core Client Demographic | Socio-Economic Development Goal |
|---|---|---|---|
| Joint Liability Group (JLG) | Social Collateral / Peer Guarantee | Rural Women & Self-Help Collectives | Grassroots Enterprise Expansion & Zero Collateral Lending |
| Individual Enterprise Microcredit | Light Movable Assets & Cash Flow History | Informal Urban Small Merchants | Scaling Micro-Retail into Formal Commercial SMEs |
| Mobile Digital Micro-Lending | Alternative Telemetry & Mobile Money Data | Unbanked Rural Youth & Gig Workers | Instant Liquidity for Emergency Working Capital |
| Agricultural Microinsurance | Parametric Weather & Satellite Soil Index | Smallholder Subsistence Farmers | Hedges Drought and Crop Failure Insolvency |
Thematic Directory & Technical Resource Guides
Institution Types & Operational Models
Frequently Asked Questions
How does a Joint Liability Group (JLG) function in microfinance?
In a JLG, a small group of borrowers (typically 4 to 10 peers) guarantees each other's loans; if one member faces repayment difficulty, the group collectively assists, creating powerful social accountability that replaces physical asset collateral.
Why do microfinance institutions specifically target women borrowers?
Extensive empirical research shows that women reinvest upwards of 90% of their earnings back into household nutrition, children's education, and family healthcare, generating far greater multigenerational community impact than lending to men alone.
How do digital microfinance banks differ from traditional high-street brick-and-mortar banks?
Digital microfinance banks operate branchless models via mobile apps and localized agent points of sale (POS), enabling low-value, high-frequency transactions with minimal overhead costs that traditional branch banking cannot economically serve.